

Table of Contents
- Why Investors Need Alternatives to Traditional Mortgage Qualification
- What is a DSCR Loan and How It Works for Rental Properties
- Bank Statement Loans: Qualifying Without Tax Returns
- Non-QM Investment Property Loans Explained
- Investment Property Loan Down Payment Requirements
- Documentation Checklist: What Lenders Want Instead of Tax Returns
- The Cost of Capital Trade-Off: Understanding Non-QM Pricing
- Frequently Asked Questions
Last Updated: September 23, 2026
Why Investors Need Alternatives to Traditional Mortgage Qualification
Traditional mortgage lenders rely heavily on tax returns to verify income and assess borrower creditworthiness. For real estate investors, this creates a significant problem. Many investors operate through multiple entities, claim depreciation and deductions that reduce reported income, or reinvest profits in ways that don’t show up clearly on tax returns.
The result? Qualified investors get rejected by banks that can’t see the full financial picture.
This is where investment property financing without tax returns becomes essential. Alternative lending programs exist specifically for investors whose income structure doesn’t fit the traditional mold. Understanding these options is critical if you’re scaling a rental portfolio or buying your first investment property.
At Lender Luke Powered By The Mortgage Exchange, we work with investors across North Jersey and Cincinnati, Ohio, who face exactly this challenge. We can help clients explore investment property loans using bank statements, profit-and-loss statements, and asset-based documentation instead of relying solely on personal tax returns.
What is a DSCR Loan and How It Works for Rental Properties
A DSCR loan (Debt Service Coverage Ratio loan) is a financing option designed specifically for investment property owners. Instead of qualifying based on personal income, DSCR loans evaluate the rental property’s cash flow to determine if it can cover the mortgage payment.
The calculation is straightforward: DSCR = Annual Rental Income ÷ Annual Debt Payments. If a property generates enough rental income to cover the loan payment with room to spare, the borrower qualifies.
Here’s why this matters for investors:
- No personal tax returns required. The property’s income speaks for itself
- Rental income is the focus. Depreciation deductions don’t reduce qualification amounts
- Multiple properties can be evaluated. You can qualify based on portfolio performance, not just individual property cash flow
- Self-employed investors can qualify. Income documentation flexibility is built into the program
Most DSCR programs require a minimum DSCR of 1.0 to 1.25, meaning the property must generate at least that multiple of the annual debt payment. A property generating $50,000 in annual rental income with a $40,000 annual mortgage payment has a DSCR of 1.25, a strong position for approval.
DSCR loans typically come with higher interest rates than conventional mortgages because they carry more risk for lenders (Examining the Relationship Between Loan Pricing and Credit Risk). However, the trade-off is clear: you access capital when traditional banks won’t approve you.
Bank Statement Loans: Qualifying Without Tax Returns
Bank statement loans are a direct alternative to tax-return-based qualification. Lenders review 12-24 months of business bank statements to verify income instead of requesting tax returns.
For investors, this approach offers several advantages:
- Shows actual cash deposits. Bank statements prove money moved in and out of your accounts
- Captures business expenses. You can document legitimate write-offs without reducing your qualification amount
- Works for newer investors. If you bought a property recently, you may not have two years of tax returns yet
- Flexible for seasonal income. Lenders average deposits over time, smoothing out months with lower activity
The underwriting process is more detailed with bank statement loans. Lenders examine:
- Deposit patterns and consistency
- Business account activity
- Expense documentation
- Reserves and liquid assets
Most bank statement loan programs require 24 months of statements, though some accept 12 months if the borrower has strong reserves. You’ll also need to provide documentation explaining any large irregular deposits or withdrawals.
Keep your business bank accounts organized and separate from personal finances. Lenders can trace deposits more easily when your business income is clearly distinct from personal money movement.
Non-QM Investment Property Loans Explained
Non-QM loans (Non-Qualified Mortgage loans) are mortgages that don’t meet the strict guidelines set by government-sponsored enterprises like Fannie Mae and Freddie Mac. For investment properties, non-QM programs are often the only path forward when traditional qualification fails.
Non-QM investment property loans can be structured around:
- Asset-based lending. Borrowers qualify based on liquid assets and reserves, not income
- Stated income programs. You declare income; the lender verifies it through bank statements rather than tax returns
- Portfolio lending. Some lenders hold loans in their own portfolio instead of selling them, allowing more flexibility
- Alternative documentation. P&L statements, business licenses, and bank statements replace tax returns
The key difference between non-QM and conventional loans is flexibility. Non-QM programs acknowledge that real estate investors often have complex financial situations that don’t fit standard underwriting boxes.
However, non-QM loans come with trade-offs. Interest rates are typically higher, down payment requirements may be larger, and closing costs can exceed conventional mortgages. The lender is taking on additional risk by accepting alternative documentation, and that risk is reflected in the loan terms.
Schedule A Free Mortgage Consultation →
Non-QM loans aren’t a backup option, they’re the right tool for the job when you’re an investor with non-traditional income documentation. The higher cost is the price of access to capital that conventional lenders won’t provide.
Investment Property Loan Down Payment Requirements
Down payment requirements for investment property loan programs vary widely depending on the loan type and lender.
Here’s what you typically need to know:
| Loan Type | Typical Down Payment | Notes |
|---|---|---|
| DSCR Loans | 20-25% | Higher DSCR ratios may allow lower down payments |
| Bank Statement Loans | 20-30% | Depends on cash reserves and property type |
| Non-QM Programs | 15-30% | Asset-based programs may accept lower down payments |
| Conventional (with tax returns) | 15-20% | Lowest down payment option if you qualify |
Down payment requirements are often tied to the property type. Single-family rentals typically require lower down payments than multi-unit properties. Commercial investment properties may require 25-30% down regardless of loan program. Securing favorable terms on these assets remains secondary to the initial challenge of finding investment property deals that offer sufficient cash flow to justify the capital outlay.
Lenders also consider your cash reserves. If you have substantial reserves (6-12 months of mortgage payments in liquid assets), some programs allow lower down payments. This demonstrates your ability to handle vacancies or unexpected expenses.
Don’t assume you need 25% down just because you’re an investor. Some non-QM and asset-based programs accept 15-20% down. Shopping around with lenders experienced in investment property financing can save you tens of thousands of dollars.
Documentation Checklist: What Lenders Want Instead of Tax Returns
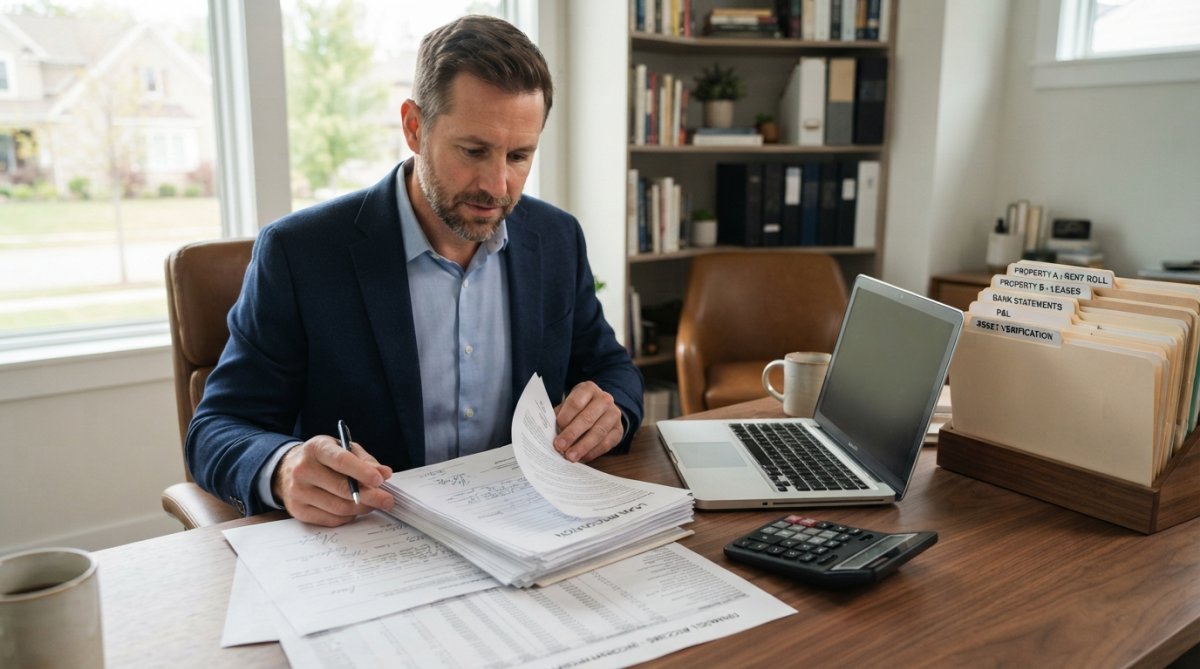
When you’re applying for investment property financing without tax returns, lenders need to verify your income and financial stability through alternative documentation. Here’s exactly what to prepare:
Required Documentation:
- 12-24 months of business bank statements (clearly labeled with account holder name)
- 12-24 months of personal bank statements (to show reserves and financial stability)
- Profit and loss statement for the current year (prepared by an accountant or from your accounting software)
- Business license or registration documents
- Lease agreements for rental properties (to verify rental income)
- Property tax statements or mortgage statements (proof of property ownership)
- Explanation letter for any large deposits or irregular transactions
- Proof of liquid assets (investment accounts, savings, certificates of deposit)
- Current credit report authorization
Optional but helpful documentation:
- Accountant letter verifying business income
- Portfolio summary showing all properties owned
- Rent roll showing all tenants and lease terms
- Property appraisals or recent purchase agreements
The key is organization. Create a folder for each property and each year’s documentation. Lenders process applications faster when everything is clearly labeled and easy to find.
Many investors make the mistake of waiting until they apply to gather documentation. Start collecting bank statements and organizing records now, even if you’re not applying for a loan yet. You’ll be ready when the right property appears.
The Cost of Capital Trade-Off: Understanding Non-QM Pricing
Using investment property financing without tax returns comes with a real cost. Non-QM loans, DSCR loans, and bank statement programs typically charge higher interest rates than conventional mortgages.
Here’s why lenders charge more:
- Higher risk. Alternative documentation is less standardized than tax returns. Lenders can’t rely on IRS verification
- Smaller market. Non-QM loans are sold to specialty investors, not government-sponsored enterprises. That costs the lender money
- Manual underwriting. Each application requires more hands-on review, increasing origination costs
- Portfolio risk. Lenders holding these loans in-house face more uncertainty about borrower performance
The interest rate difference can vary depending on the loan program and your financial profile. This difference can mean additional payments compared to conventional options.
However, the trade-off is often worth it. If a conventional lender rejects you, the alternative isn’t a slightly higher rate, it’s no loan at all.
Frequently Asked Questions
Can I get investment property financing without showing tax returns?
Yes. DSCR loans, bank statement loans, and non-QM programs allow lenders to qualify you based on rental income, bank statements, profit-and-loss statements, and asset verification instead of tax returns. Lenders verify your ability to service debt through the property’s cash flow rather than your personal income documentation. The specific program depends on your financial profile and the property’s rental income potential.
What are DSCR loan requirements for a rental property?
DSCR (Debt Service Coverage Ratio) loans focus on the property’s rental income rather than your personal income. Most lenders require a minimum DSCR, meaning the property’s monthly rental income must cover a certain percentage of your total monthly debt payments. You’ll typically need 20-25% down and proof of liquid assets. The property must be an investment or second home, not your primary residence.
What documentation do I need instead of tax returns?
Lenders typically request 12-24 months of personal and business bank statements, profit-and-loss statements, rental agreements or lease contracts for the property, a property appraisal, proof of liquid assets (savings accounts, investment accounts), and a personal credit report. Some programs accept signed affidavits of income or stated-income documentation. Each lender’s requirements vary, so confirm the specific list with your loan officer before applying.
Are non-QM investment property loans more expensive than traditional mortgages?
Non-QM loans typically carry higher interest rates and origination fees than conventional mortgages because they involve greater underwriting risk and manual review. The exact difference depends on your credit score, down payment, DSCR, and the lender. Rather than assume a specific cost, request a loan estimate from your lender to compare rates and fees side-by-side with traditional options. This transparency helps you weigh the trade-off between qualification ease and overall borrowing cost.

